More than half of Texas residential flood insurance claims occurred outside areas currently designated as high-risk, raising questions about flood exposure, insurance coverage, and the limitations of federal flood maps.
When homeowners think about flood risks, they often look to the Federal Emergency Management Agency (FEMA) flood maps to determine whether their property is in danger. However, new research suggests that living outside a designated high-risk flood zone does not necessarily mean a home is safe from flooding.
A new analysis from Anidjar & Levine found that 52.1% of classifiable residential flood insurance claims in Texas involved properties located outside FEMA’s current high-risk flood zones.
That makes Texas the only state among the 30 qualifying states where the majority of these claims occurred outside designated high-risk areas.
The findings highlight a growing concern for homeowners nationwide: Flooding does not always follow the boundaries established on federal flood maps.
Texas Tops the List for Flood Claims Outside High-Risk Areas
According to the study, which examined National Flood Insurance Program (NFIP) residential claims for losses between 2014 and 2024, Texas recorded the highest percentage of claims associated with properties outside current high-risk flood zones.
Nationally, 28.1% of classifiable residential flood claims fell into this category, placing Texas a significant 24 percentage points above the national average.
Maryland followed with 45.9%, while New York, Virginia, and California rounded out the top five.
States With the Highest Percentage of Flood Claims Outside High-Risk Zones
| Rank | State | Outside-Zone Claims |
|---|---|---|
| 1 | Texas | 52.1% |
| 2 | Maryland | 45.9% |
| 3 | New York | 39.0% |
| 4 | Virginia | 36.2% |
| 5 | California | 35.6% |
| 6 | Ohio | 33.3% |
| 7 | Tennessee | 30.4% |
| 8 | Wisconsin | 30.3% |
| 9 | Oklahoma | 30.0% |
| 10 | Connecticut | 29.1% |
| 30 | Florida | 11.4% |
| — | National Benchmark | 28.1% |
Source: Anidjar & Levine analysis of NFIP residential flood claims, 2014–2024, compared with current flood-zone classifications.
One particularly interesting finding is that several inland states, including Ohio, Tennessee, Wisconsin, and Oklahoma, exceeded the national benchmark.
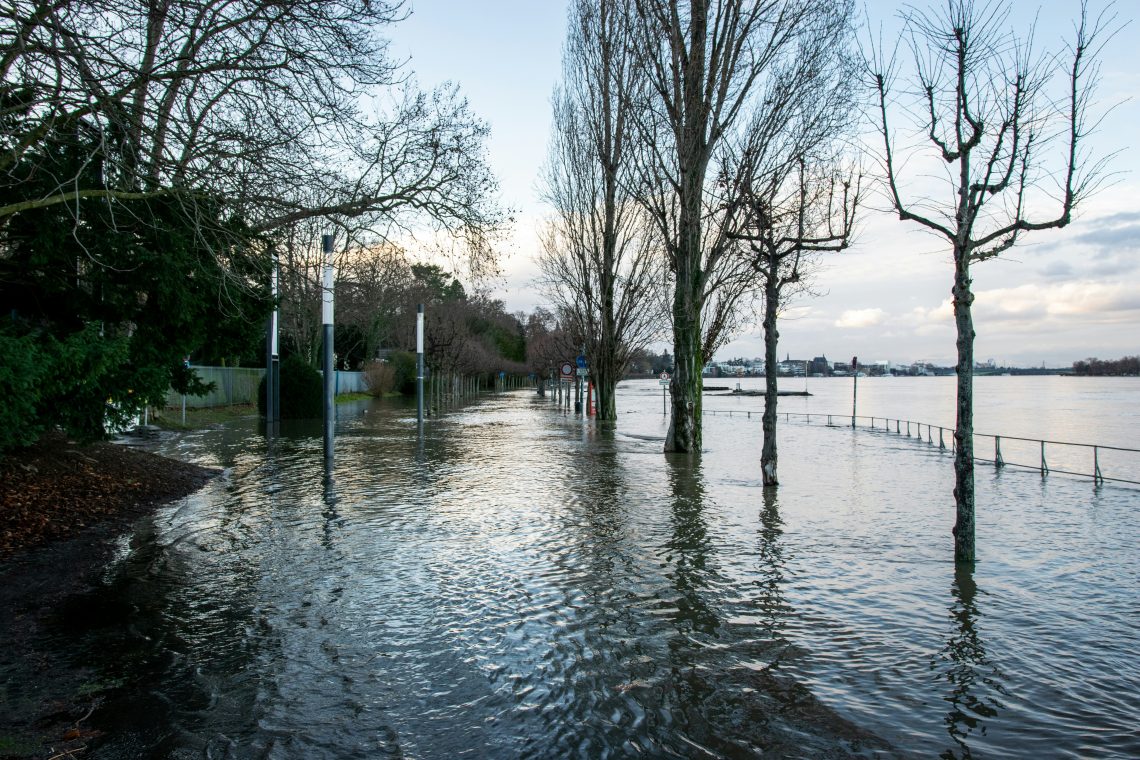
This suggests that flood damage is not exclusively a coastal concern. Heavy rainfall, overflowing rivers, drainage problems, and flash flooding can threaten homes hundreds of miles from the ocean.
Florida, despite its well-known hurricane and flooding exposure, recorded the lowest outside-zone percentage among qualifying states at 11.4%.
However, that does not mean Florida experiences fewer floods. The rankings measure the proportion of insured claims outside designated zones, not the overall frequency or severity of flooding.
Millions of At-Risk Homes May Fall Outside FEMA’s High-Risk Zones
The findings become even more concerning when considered alongside a separate October 2026 report from the U.S. Government Accountability Office (GAO).
The federal report examined how flood risk classifications relate to insurance participation and identified millions of properties with modeled flood exposure outside FEMA’s designated high-risk areas.
As of April 2026, the GAO estimated:
| Property Classification | Properties | NFIP Coverage Rate |
|---|---|---|
| Inside FEMA high-risk areas | 4.02 million | 42.9% |
| High modeled risk outside designated areas | 12.80 million | 6.6% |
| Moderate modeled risk outside designated areas | 2.51 million | 4.2% |
The difference is substantial.
While approximately 42.9% of properties within FEMA’s high-risk areas carried NFIP coverage, only 6.6% of properties classified as high-risk by the GAO’s modeling but located outside those boundaries had coverage.
That represents a 36.3-percentage-point gap in flood insurance participation.
For homeowners, the implications can be financially devastating.
A family might believe flood insurance is unnecessary because their mortgage lender does not require it, only to discover after a major storm that their standard homeowners insurance policy generally does not cover flood damage.
Flood Insurance Coverage Is Declining in Texas
Adding to the concern is a decline in flood insurance participation.
According to Realtor.com’s July 2026 Housing and Climate Risk Report, Texas experienced the largest year-over-year decrease in NFIP contracts among states between May 2025 and May 2026.
Flood insurance contracts in Texas dropped 7.8%, compared with a national decline of 4.5%.
Oklahoma, another state with a relatively high percentage of outside-zone claims, experienced a 6.9% decrease.
These declining numbers raise questions about how many homeowners could face significant out-of-pocket expenses following a major flooding event.
Is Flood Insurance Becoming Too Expensive?
Affordability may be part of the challenge.
Realtor.com’s report also noted that the median annual NFIP premium was projected to increase from $689 in December 2022 to a long-term target of $1,288 under FEMA’s Risk Rating 2.0 pricing system.
For households already struggling with rising mortgage payments, property taxes, utilities, and homeowners insurance premiums, additional flood coverage may feel like another expense they cannot afford.
However, the financial consequences of experiencing a flood without insurance can be far greater than the annual cost of a policy.
Why FEMA Flood Maps May Not Tell the Whole Story
FEMA’s flood maps play an important role in identifying areas exposed to significant flooding risks. They also help determine when federally backed mortgage lenders must require flood insurance.
But these maps are not intended to guarantee that properties outside designated high-risk areas will never flood.
Flooding can occur because of several factors, including:
- Heavy rainfall that overwhelms local drainage systems
- Flash flooding following severe thunderstorms
- Rivers and streams overflowing their banks
- Tropical storms and hurricanes moving inland
- Rapid development that changes how water flows through neighborhoods
- Flooding caused by hazards not fully reflected in existing maps
The GAO’s research found that properties inside Special Flood Hazard Areas were approximately 24 percentage points more likely to carry NFIP insurance than comparable properties outside those areas, even after accounting for modeled flood exposure and other factors.
This suggests that official flood-zone designations are strongly associated with whether homeowners purchase flood insurance.
It also reinforces an important distinction: Not being required to purchase flood insurance is not the same as not needing it.
What Homeowners Should Know About Flood Insurance
Whether you live in Texas, North Carolina, Florida, or another state, these findings offer a reminder that understanding your property’s flood exposure is an important part of protecting your home.
Here are several practical steps homeowners can consider.
1. Check Your Property’s Flood Zone
Start by visiting the FEMA Flood Map Service Center to review your property’s official flood designation.
Remember that these maps are one tool for understanding risk, not a guarantee that flooding cannot occur.
2. Review Your Homeowners Insurance Policy
Many homeowners assume their existing insurance covers all types of water damage.
Unfortunately, standard homeowners insurance typically excludes damage caused by flooding.
Contact your insurance provider to understand exactly what your policy covers and whether separate flood insurance would be appropriate.
3. Compare Flood Insurance Options
Homeowners can explore coverage through the National Flood Insurance Program and participating private insurers.
Premiums, coverage limits, exclusions, and waiting periods can vary, making it worthwhile to compare available options before purchasing a policy.
4. Consider Your Home’s Flooding History
Even if your property is outside a designated high-risk area, previous flooding in your neighborhood may provide useful information.
Local emergency management offices, municipal flood records, and neighbors may help you understand whether your community has experienced flooding.
5. Prepare Before Severe Weather Arrives
Protecting your home involves more than purchasing insurance.
Keeping important documents in waterproof containers, maintaining drainage systems, creating an emergency evacuation plan, and documenting valuable belongings can make recovery easier if flooding occurs.
Federal Officials Are Reexamining Flood Insurance Requirements
The issue is also receiving attention at the federal level.
In its October 1, 2026, report, the GAO recommended that Congress consider expanding mandatory flood insurance criteria to account for additional flooding hazards, particularly heavy rainfall.
The recommendation reflects concerns that existing requirements may not fully account for properties facing significant flood exposure outside FEMA’s designated high-risk zones.
The National Flood Insurance Program’s current authorization is scheduled to expire on December 11, 2026, placing renewed attention on the future of federal flood insurance policies and consumer protections.
Any changes to insurance requirements could affect homeowners, mortgage lenders, and communities across the country.
The Bottom Line: Flood Risk Doesn’t Stop at a Map Boundary
The latest research provides an important reminder that flood exposure extends beyond the areas traditionally considered most vulnerable.
Texas stands out because more than half of its classifiable residential flood insurance claims from 2014 through 2024 involved properties outside FEMA’s current high-risk zones.
Meanwhile, millions of properties nationwide may face substantial modeled flood exposure without carrying flood insurance.
Although historical insurance claims cannot predict whether an individual property will flood, they demonstrate why homeowners should look beyond official flood-zone classifications when evaluating their risks.
Your home may be outside a high-risk flood zone, but that doesn’t mean it is outside the reach of floodwaters.
Taking time to understand your property’s exposure, review your insurance coverage, and prepare for unexpected weather could help protect one of your most valuable investments.
For more information, read the full Anidjar & Levine study, Beyond High-Risk Flood Zones: The Overlooked Cost of Flood Damage.
Editor’s Note: The state rankings compare historical NFIP claims with current flood-zone classifications. They do not measure the probability of flooding for individual homes or establish whether a property’s designation was the same when a loss occurred.